Renting a home comes with its own set of money challenges. Without a mortgage to build equity, it can feel like your rent payment just disappears every month. However, renting families can still build real financial security. It just takes a bit of planning and a few smart habits along the way.
Establishing an Emergency Fund
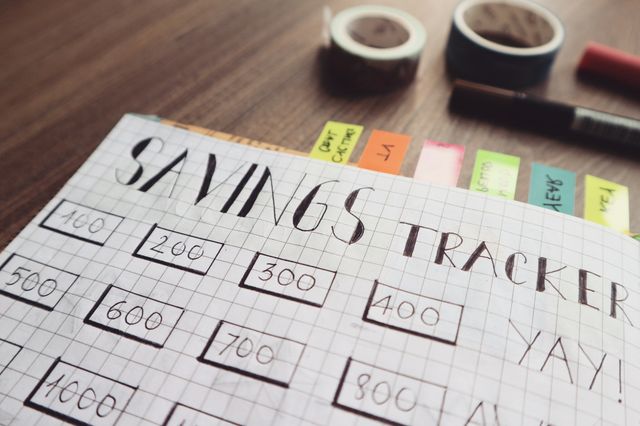
A broken-down car or a sudden medical bill can be challenging to deal with if you don’t have savings to fall back on. That’s why an emergency fund matters so much when you’re renting. A few ways to get started include:
- Automate a small transfer every payday, even just $10 or $20
- Keep the account at a different bank so it’s less tempting to touch
- Add windfalls like tax refunds or bonuses straight into the fund
Aim for three to six months of living expenses eventually, but don’t stress if you’re starting from zero.
Budgeting for Rent and Utilities
Rent and utilities usually take up the biggest chunk of a family’s monthly budget. Getting a handle on these costs is one of the best examples of financial goals you can set for your household.
Start by writing down every expense, even small ones like streaming subscriptions. If you need help setting financial goals around monthly spending, try the 50/30/20 rule: 50% for needs, 30% for wants, and 20% for savings. A few quick ways to trim utility costs:
- Switch off lights and unplug devices you’re not using
- Seal drafty windows and doors to cut heating costs
- Compare internet and phone providers once a year
Saving for Future Home Ownership
Many renting families dream of owning a home someday. Start by figuring out roughly how much a down payment might cost in the area you’d like to live in. Open a dedicated savings account just for this goal, separate from your emergency fund. Small, regular contributions build up faster than you’d expect. If you want to learn more about financial goals and how to set them for a home purchase, break the big number into smaller yearly targets.
Managing Debt Efficiently
Debt is common, but it can quietly eat away at your ability to save. Credit cards, car loans, and student loans each come with their own interest rates, so it helps to know exactly what you owe.
Start by listing all your debts along with their interest rates. Focus extra payments on the debt with the highest interest first, while still making minimum payments on the rest. This approach, known as the avalanche method, saves you the most money over time. If you’re unsure where to begin, take time to learn how to set your financial goals around debt.
Planning for Retirement
It’s easy to put off retirement planning when you’re focused on rent and daily bills, but starting early makes a huge difference. Even small contributions now have decades to grow before you’ll need them.
If your employer offers a retirement plan with matching contributions, try to contribute enough to get the full match. That’s essentially free money. If that’s not available, look into an individual retirement account instead. Whatever your income level, it’s worth taking time to set financial goals for your future, even if retirement feels far away right now.
Endnote
With an emergency fund, a solid budget, and a plan for debt, homeownership, and retirement, renting families can build real stability. Start small, stay consistent, and adjust your goals as life changes. Every step forward counts, no matter how small it feels today.